Three Ways to Handle a Loss You Could Claim, and What Each One Leaves Behind
Paying it yourself, asking a question, or filing a claim are three different transactions with three different afterlives. How to tell which one a given loss deserves.
Hilde Brekke·4 min read·1,000 words
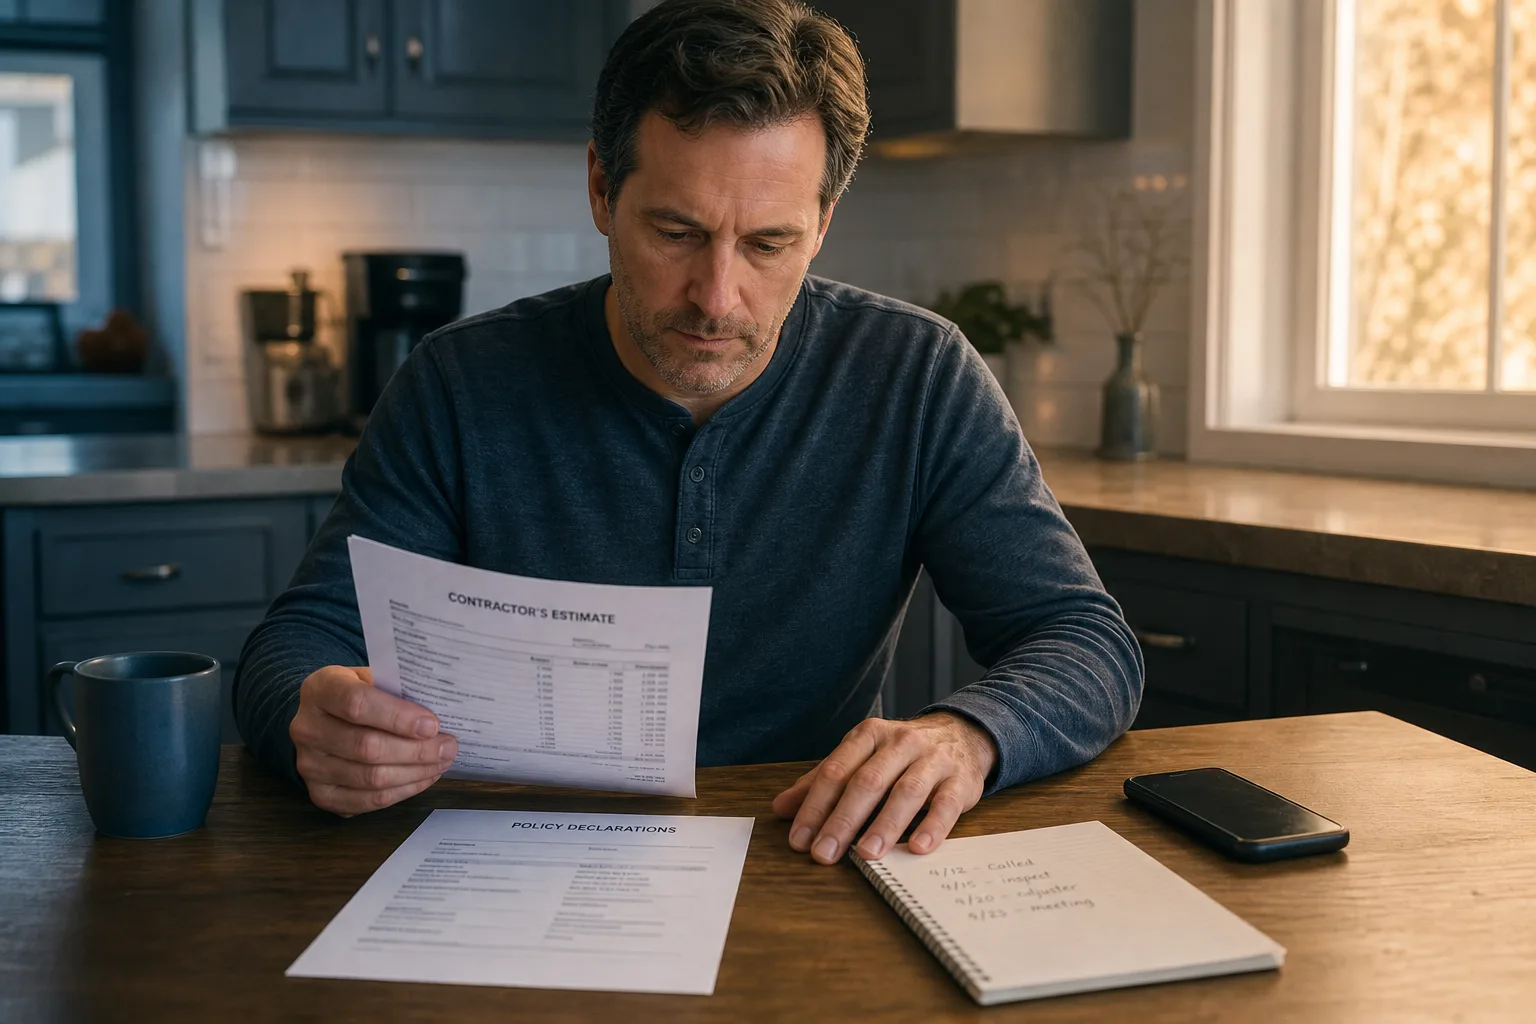
The moment that decides your next renewal is usually a phone call you have not made yet. Something has failed, the damage is visible but not catastrophic, and you are standing in the room doing arithmetic against a deductible you half remember. Three routes are open. You can absorb the cost and tell nobody, you can call and ask a question without asking for money, or you can file. They feel similar from the kitchen. They are not similar at all in what they leave behind, and the difference is worth understanding before the adjuster's number is in your phone.
The three doors, described from your side of them
Paying it yourself is the quietest option and the one most people undersell. You get a contractor, you pay, nothing is reported, and your loss history stays where it was. Asking a question is the middle route, and it is the one carriers describe least clearly: you call, describe a situation, ask whether it is the kind of thing the policy contemplates, and try to end the call without a claim number. Filing is the third door. Once you have a claim number, you have a file, and a file has a life beyond the check.
What customers usually discover is that the middle door is narrower than it looks. Some carriers log any substantive damage conversation as a claim inquiry, some log it as a claim with a zero payout, and some genuinely treat it as a question and record nothing. The variation is not sinister, it is just uneven practice across companies. So the useful move on that call is to ask directly, early, whether the conversation is being opened as a claim, and to write down the name of the person who answered you and the date.
What actually goes on the record
Loss history follows the property and the person through industry databases that carriers query when you apply or renew, and those reports fall under the Fair Credit Reporting Act, which the Federal Trade Commission is responsible for enforcing. That gives you two rights worth knowing about before you need them: you can request your own loss history file, and you can dispute an entry that is wrong. People discover errors more often than you would expect. A claim that was withdrawn shows as paid, a claim filed by a prior owner attaches to the address, or a single event appears twice under slightly different dates.
The practical consequence is that your record is not a rumor, it is a document, and documents can be read and corrected. If you are within a year of shopping your policy, pull the file first. A renewal quote that came back higher than you expected sometimes traces to an entry you can have removed, and that is a much better conversation than arguing about your loyalty or your years without a payout.
Which marks matter and which are only cosmetic
Not all claims weigh the same, and this is where judgement has to be built rather than looked up. A single hail event in a county where everyone's roof was hit reads differently from a kitchen supply line that let go, because the first is weather and the second is maintenance. Underwriters look hardest at water. A water claim tends to invite a second question about whether the condition that caused it has been fixed, and it can shape the deductible or the endorsements you are offered next time. Wind and hail, especially in a documented regional event, sit far lighter on the file.
Frequency is the other thing being judged, and it is judged more harshly than size. Two modest claims in three years reads worse in most underwriting than one large claim in ten, because frequency suggests a pattern and severity suggests bad luck. That asymmetry is the single most useful thing to hold in your head when the damage is small. A twenty-two hundred dollar loss against a one thousand dollar deductible recovers twelve hundred dollars and spends a slot on your record that you may want in two years when a tree comes through the roof.
Running the arithmetic before you dial
Start with a contractor's written estimate rather than your own guess, because the guess is almost always low and the estimate sometimes reveals damage that changes the answer entirely. Subtract your deductible. If what remains is less than roughly a year of the premium increase you might see, the claim is probably not worth its record. That comparison requires a number you can get by asking your agent, in general terms, what a claim of this type typically does to a renewal at your carrier. Agents answer that question more freely than customers expect, and the answer is often specific enough to decide on.
Then check the clock. Policies carry prompt notice requirements, and a loss you sit on for four months while deciding can be denied on timing alone even if it was covered on the merits. The honest sequence is to get the estimate quickly, decide quickly, and if you decide to file, file within days rather than weeks. Deciding not to claim is a legitimate decision, but it should be made deliberately and in writing to yourself, not by letting the deadline pass while you think about it.
The version of this that goes well
Households that come through a loss with both a repaired house and an intact renewal tend to do the same handful of things. They photograph everything before touching it, they stop the damage from spreading, they get one real estimate before calling anyone, they ask whether a call is being logged, and they keep a dated page of who said what. That page costs nothing and settles most later disputes on its own. The judgement you are building is not about avoiding claims. It is about knowing which losses your policy exists to absorb and which ones you were always going to pay for anyway.