Insuring a Ring? The Date on the Appraisal Decides More Than the Number
An appraisal is a dated opinion written for one purpose, and what it buys you at claim time depends on the policy language and the state you file in.
Hilde Brekke·4 min read·855 words
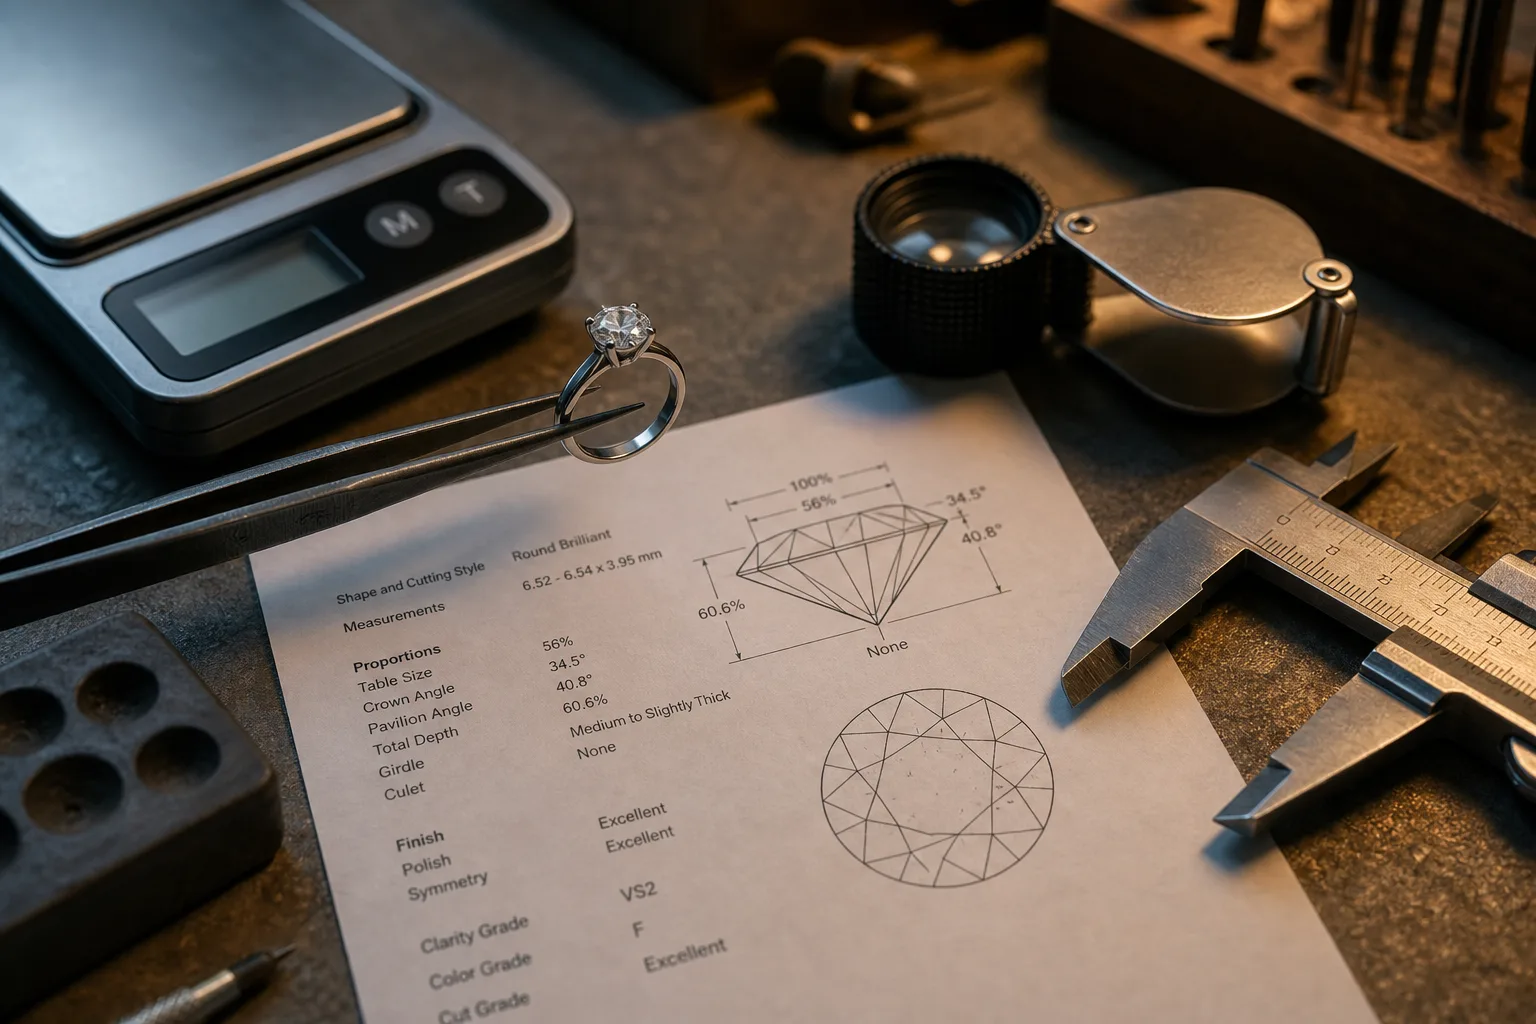
The document in the safe deposit box says the ring is worth a number, and most people treat that number as settled, the way a deed is settled. It is not settled. An appraisal is one person's opinion of value, written on a particular day, for a particular purpose, using a particular market as its reference. Change any of those four and the number moves. Insurers know this, which is why the schedule attached to your homeowners policy is quietly governed by an interval most policyholders have never looked for, and why a claim on a fifteen-year-old appraisal rarely goes the way the owner expected.
What the paper is actually claiming
Read the purpose line first, because it controls everything below it. An appraisal written for insurance replacement states what it would cost to buy a comparable item at retail, in a defined market, today. An estate appraisal states fair market value, which is what a willing buyer would pay a willing seller, and it is usually a good deal lower. A donation appraisal answers to the IRS and its own substantiation rules. Three documents, one ring, three defensible numbers. Handing an insurer an estate appraisal and expecting a replacement payout is a category error, and it is the most common one.
Judging the finish on the document itself
Good appraisal work looks like good bench work: it is specific where specificity is hard. I want measured stone dimensions rather than a stated carat weight lifted from a receipt, metal fineness tested rather than assumed, a plot or a clear description of inclusions, mounting style, finish, and any evidence of prior repair or resizing. I want photographs that show the piece from more than one angle, and I want the appraiser's methodology and comparables named. Vague adjectives are the cosmetic flaw that turns structural at claim time. An adjuster cannot replace "a fine white diamond of good clarity" with anything, because the phrase describes nothing.
The Federal Trade Commission is responsible for the guidance governing how jewelry is described in commerce, which is why terms like treated, lab-grown, and cultured carry defined meanings rather than decorative ones. An appraisal that uses those words carefully is telling you the appraiser is working to a standard. One that avoids them, on a stone that plainly has been treated, is telling you something too.
Why it expires, and who decides the interval
Nothing about the ring changed. The market underneath it did. Gold and platinum move, colored stone supply moves, certain cuts and periods come into favor and take retail prices with them, and the labor rate at the bench that would build a replacement moves with everything else. A replacement-cost figure is a snapshot of a market, so it ages the way a market ages. Most carriers handling scheduled personal property expect a refreshed appraisal on a stated cycle, commonly a few years, and the requirement usually lives in the endorsement rather than the declarations page. Ask your agent for the interval in writing.
There is a second reason to refresh that has nothing to do with prices rising. Detail improves. An appraisal written in 1998 by a jeweler who eyeballed the stone and typed a paragraph is a weaker instrument than one written now with measurements, images, and a lab report attached, and the weaker instrument is the one your family will be holding if the piece is stolen.
Where the state you live in changes the answer
Personal property appraisers are not licensed by the states the way real estate appraisers are. There is no state credential to check, which puts the burden on you to look at professional membership, tested gemological training, and the quality of the report itself. Policy language, by contrast, is very much a state matter. Forms are reviewed by state insurance departments, so the definition of value, the appraisal clause that resolves a disputed loss amount, and the deadlines for demanding it differ from one state to the next. Coastal states add named-storm deductibles that can swallow a small scheduled loss entirely.
Local market matters just as much as local law. Replacement cost means replacement in your market, and the same platinum setting reproduced in a metropolitan retail district and in a small city are not the same invoice. Sales tax is the piece people forget: whether a settlement includes it, and at what rate, depends on where you buy the replacement. If you moved states since the appraisal was written, the number on the paper was calculated for a market you no longer live in.
Running the refresh so it holds up
Book the appraiser who will handle the piece in person, ask what the report will contain before you agree to the fee, and send the resulting document to your agent with a request that the schedule be updated and confirmed back to you. Keep the photographs somewhere that is not the house. Then put a reminder at the interval your carrier named.
The value of a current, detailed appraisal is that it argues for you when you are not in the room. That is the whole job.