First Homeowners Policy? What the Mold Exclusion Is Actually Telling You
An exclusion is an underwriter's forecast written backward, and the mold and pollution clauses tell a first-time buyer exactly which damage the company expects to see.
Joaquin Salcedo·4 min read·823 words
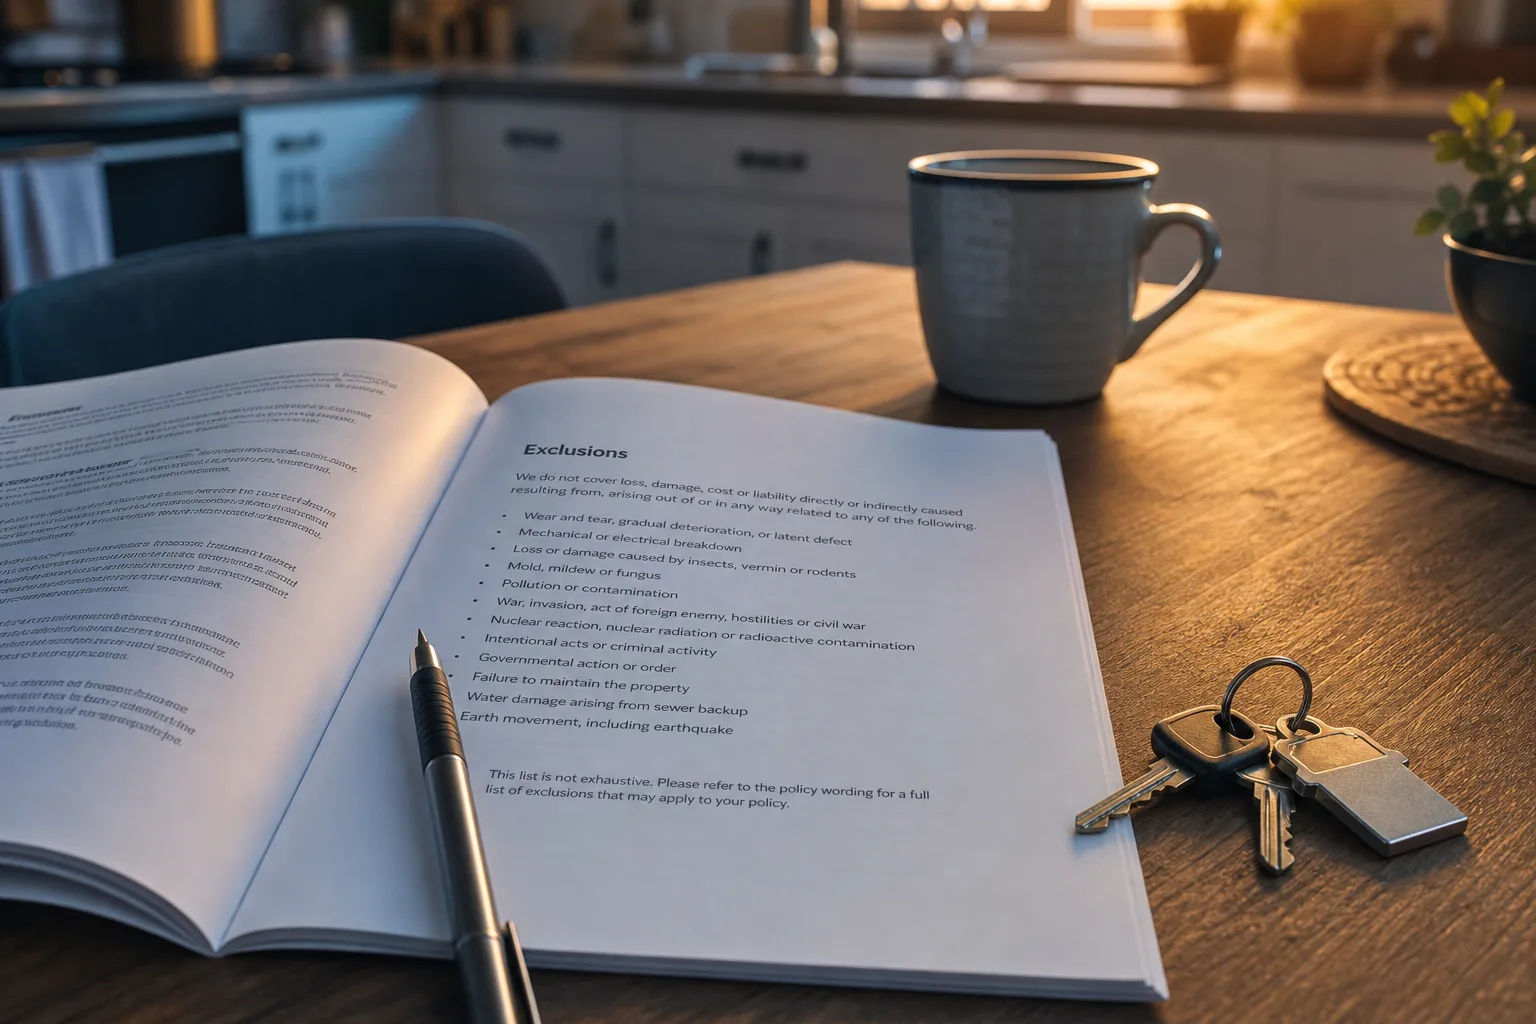
An exclusion clause is not the insurer being difficult. It is the insurer telling you, in advance and in writing, which losses it has decided are common enough, slow enough, or hard enough to price that it would rather not be in that business. Read that way, the mold paragraph in a homeowners policy stops looking like fine print designed to trap you and starts looking like a forecast written backward: these are the things we expect to happen in houses like yours. For someone buying a first policy, that reframing is most of the work.
The clause is a forecast, and the naming is part of it
Notice what the paragraph is called before you argue with what it says. Some policies exclude mold, some exclude fungi, some fold both into a longer clause covering wet rot, dry rot, bacteria and microbes, and at least one of those lists will be broad enough to catch the black speckling behind a shower wall and the musty smell in a crawlspace alike. The word chosen matters because it sets the argument you will eventually have. A claim about mold invites a debate over whether mold caused the damage. A claim about a covered water loss invites a debate over what the water did, which is a different and usually better conversation to be having.
Sudden and accidental, and the sentence that undoes it
Nearly every policy will pay for water damage that arrives suddenly and accidentally, and nearly every policy will decline water damage that arrives over weeks through a seep, a drip, or a roof that has been failing since before you owned it. The mold exclusion usually sits downstream of that split. If mold grew because a supply line burst on a Tuesday and you called someone Wednesday, many policies contain a limited remediation allowance, often capped at a modest dollar figure stated on the declarations page. If it grew because the shower pan has leaked quietly for two years, the exclusion does the whole job on its own. Those are not the same peril wearing different clothes.
What a careful read looks like next to a fast one
A barely adequate review is the one most first-time buyers get, and it is not anyone's fault: an agent quotes three carriers, the premiums are within a couple hundred dollars, and the mold language never comes up because nobody asked. A good review does four things instead. It finds the mold or fungi paragraph and reads it aloud. It finds the sublimit attached to it and writes the number down. It asks whether the carrier offers a buyback endorsement raising that limit, what the endorsement costs, and whether it applies to remediation only or also to tearing out and replacing the wall. Then it asks the same three questions of the second carrier so the premiums can actually be compared.
The pollution clause is doing quieter work than the mold clause
Alongside mold, most policies carry a pollution or contaminants exclusion, and first-time buyers almost never read it because the word sounds industrial and their house is a house. It is the clause that governs fumes. Smoke residue after a fire is usually handled elsewhere, but a heating oil release in a basement, a sewage backup without the specific endorsement, or vapor intrusion from something in the soil will land in that paragraph, and the cleanup costs there are the ones that outrun a deductible fastest. The Environmental Protection Agency is the federal body responsible for indoor air quality and mold guidance, and the exposures it concerns itself with are largely the same ones these two clauses carve out.
The health question sitting underneath the money question
What a physician worries about and what an adjuster worries about overlap, but imperfectly. The exposures that genuinely warrant clinical attention are sustained ones in air people breathe for months: chronic damp in a bedroom, a crawlspace pushing moist air up through the floor, combustion byproducts from a cracked heat exchanger or a blocked flue, sewage aerosols, disturbed lead paint dust during a renovation. A visible patch of surface mold on tile grout is a cleaning problem. Water inside a wall cavity that nobody opened is a different category, because the growth is continuous, the source is still running, and the occupants have no way to know the dose they are getting.
So the practical use of an exclusion clause, for someone reading a policy for the first time, is diagnostic rather than legal. It tells you where the carrier expects trouble, which is a reasonable proxy for where trouble actually occurs, and it points you at the maintenance that keeps a loss inside the covered category: the supply lines, the shower pan, the flue, the grading, the crawlspace vapor barrier. Fix the slow leaks and the exclusions largely stop applying to you. That is the whole design, stated plainly on a page most people skip.